AML/KYC Readiness Checklist Before a U.S. Launch
A readiness framework for higher-scrutiny businesses preparing for bank, payment-provider, vendor or professional compliance review.
Updated September 16, 2026 · Primary-source guide · Not legal or compliance advice
Start with risk, then build controls around the risk
FinCEN's guidance emphasizes customer due diligence and risk-based controls, while OFAC's framework recommends a risk-based sanctions compliance program. The right readiness package depends on the business model, customers, products, jurisdictions and transaction flows; there is no single universal checklist that fits every launch.
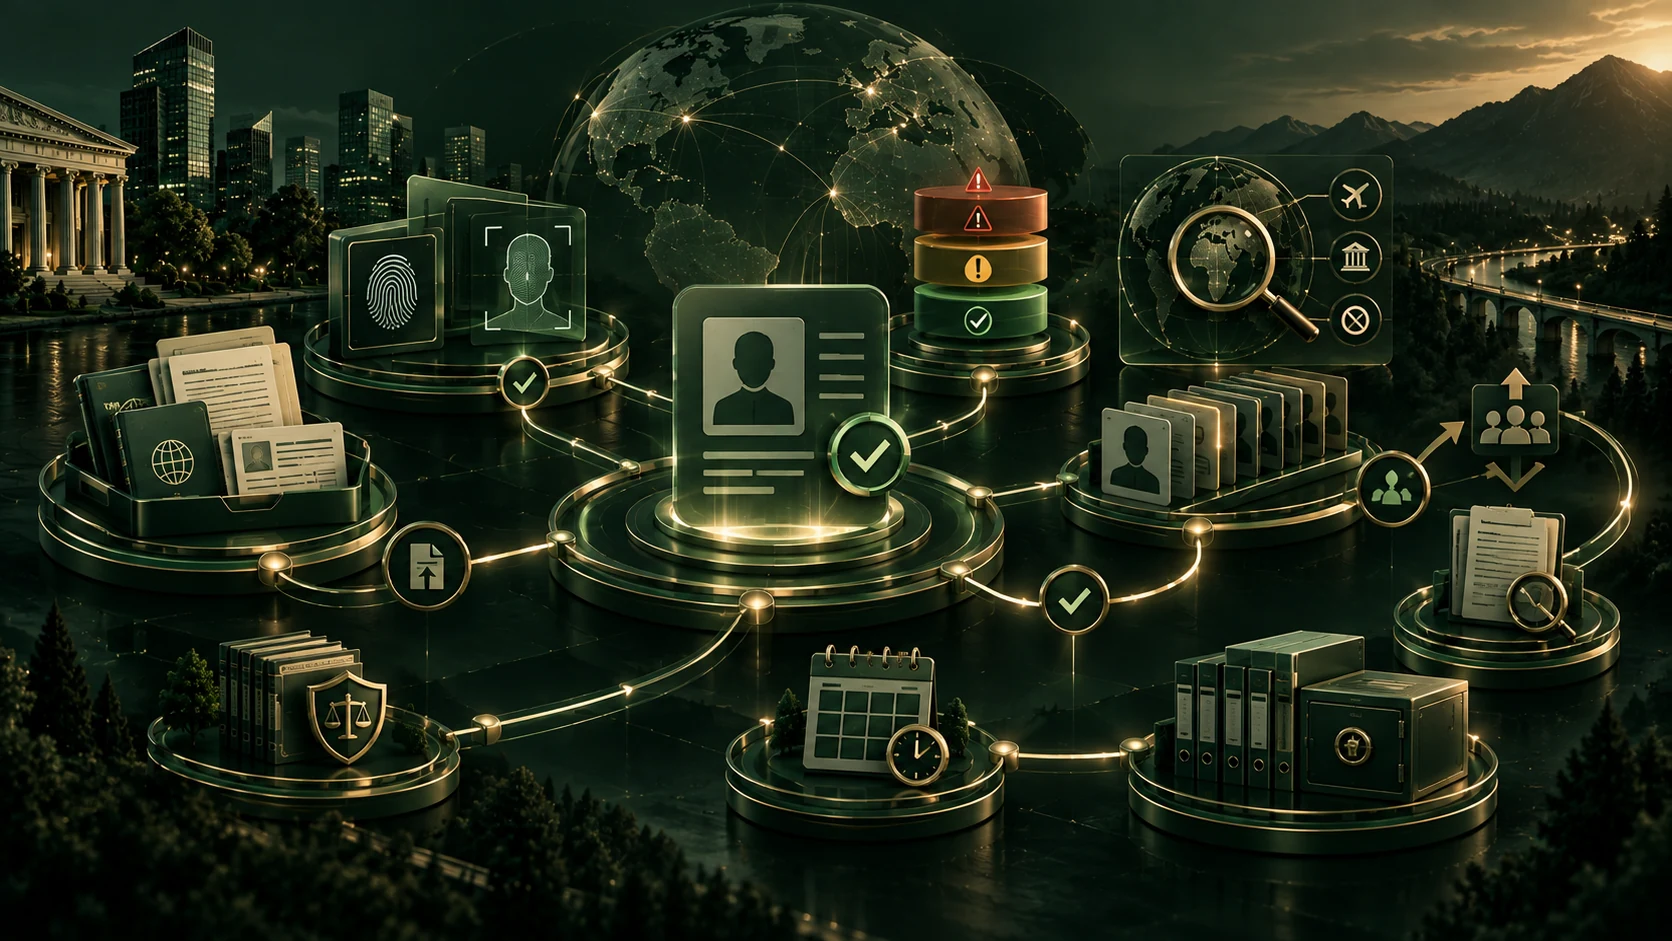
What a credible pre-launch file should address
Risk assessment
Document customers, products, geographies, transaction types, delivery channels, counterparties and higher-risk scenarios.
Customer onboarding
Define identity/document collection, beneficial-owner handling where relevant, risk tiers, review triggers, escalation and exception handling.
Sanctions controls
OFAC recommends tailored risk-based sanctions controls. Depending on the business, this can include sanctions screening, match review and escalation procedures.
Monitoring and escalation
Map what activity should trigger manual review, who investigates it, what evidence is retained, when accounts are restricted or escalated, and how suspicious activity obligations are handled if the business is subject to them.
Ownership and accountability
Assign owners for policy maintenance, training, testing, vendor oversight and regulatory updates. OFAC's framework highlights management commitment, risk assessment, internal controls, testing/auditing and training as core components of a sanctions compliance program.
- Plain-English business model and transaction-flow diagram.
- Customer and counterparty risk categories.
- Identity and business-verification requirements by customer type.
- Beneficial-owner and control-person process where relevant.
- Sanctions-screening and false-positive review process.
- Monitoring rules, review queues, escalation and case notes.
- Record-retention, access control and audit trail.
- Training, testing, policy-review and vendor-governance schedule.
Important: a readiness framework is not a legal opinion that a particular law applies or that the program is sufficient for a regulated business. Qualified compliance counsel should review obligations where required.
Sources used
FinCEN CDD / beneficial-ownership guidance · FinCEN MSB guidance library · OFAC Framework for Compliance Commitments · OFAC virtual-currency FAQ 560
Legalize coordinates readiness documentation and professional handoff. It does not replace qualified compliance counsel or guarantee regulatory, banking or vendor outcomes.