Payment Processor Readiness for Foreign Founders
Payment providers verify the business, people behind it, bank details, website and what is being sold. Foreign ownership is not automatically disqualifying, but inconsistent or incomplete information can create friction.
Updated September 16, 2026 · Provider-source guide · No approval guarantee
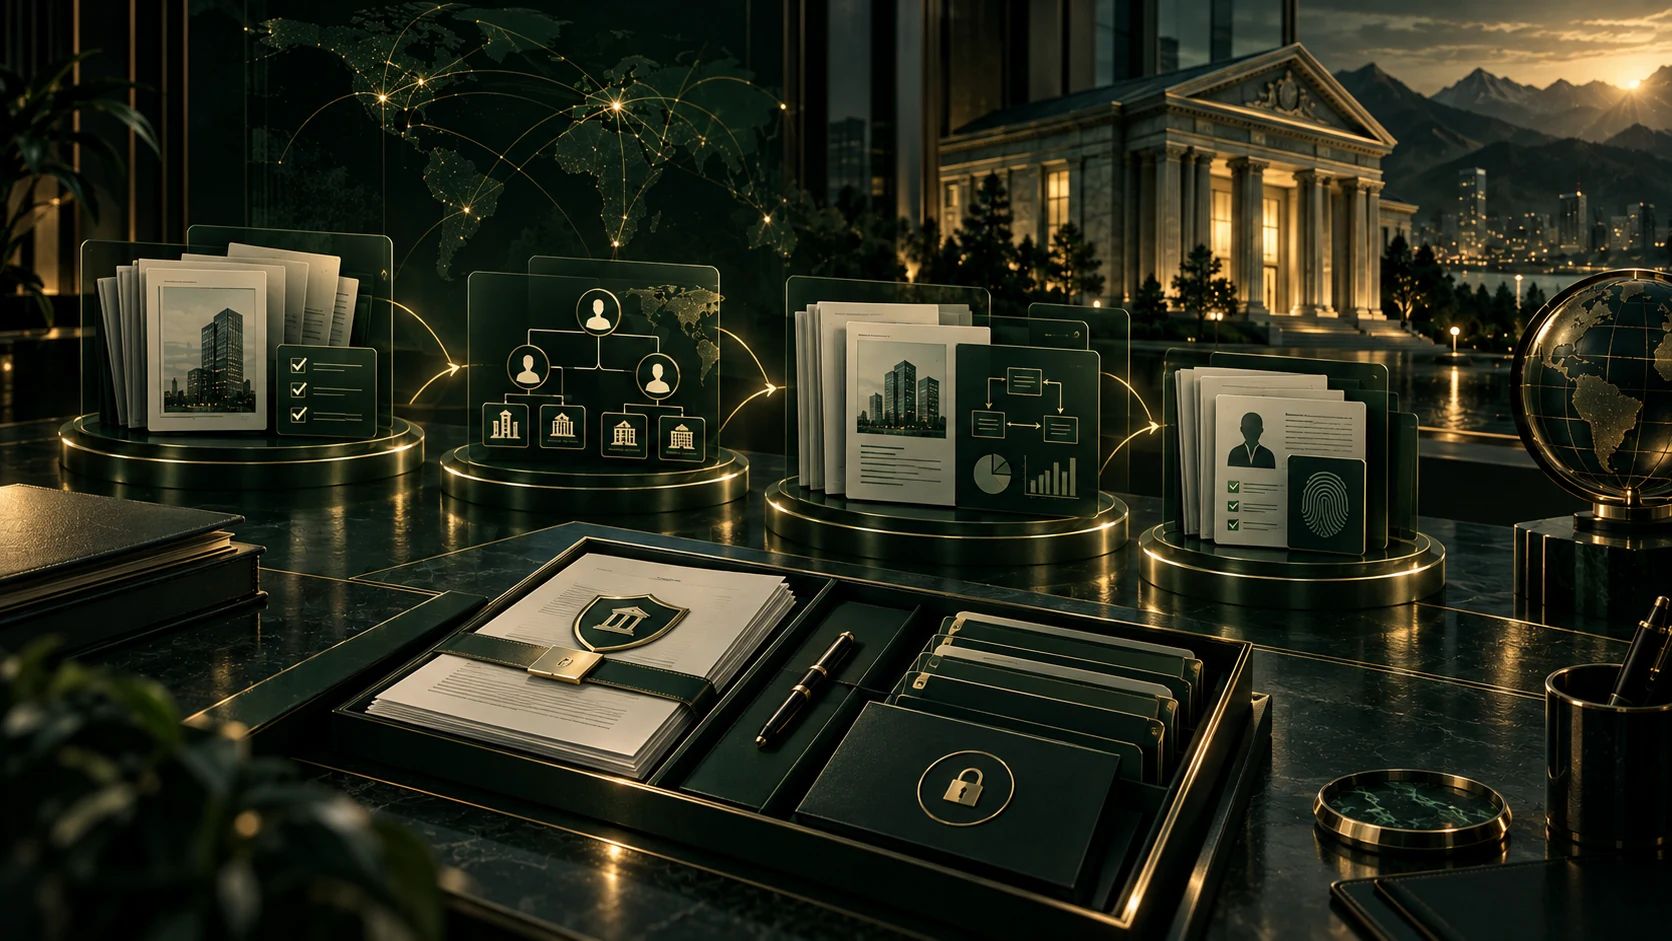
Prepare one consistent story across entity, owners, bank and website
Stripe's U.S. verification guidance says registered businesses using a U.S. Stripe account must be registered in the U.S. and provide business-location information. Stripe may verify legal entity name/type, EIN, owner or representative identity, business address, bank ownership and website information, and may request additional documentation. Other processors apply their own underwriting rules.
Entity and tax identity
Keep the legal name, entity type, EIN and formation documents consistent across your application, website, bank and corporate records.
Owners and representatives
Be ready to identify owners, representatives and people with significant control. Non-U.S. representatives may be asked for government identification.
Bank ownership
The provider may verify that the bank-account owner and the business or account owner information line up.
Make the website underwriting-ready
A live website should clearly explain what you sell, who the customer is, how the service is delivered and how users can contact the business. Provider guidance can also require or review terms, refund/cancellation information, privacy disclosures and website ownership.
Explain money flow before the provider has to guess
Document the product, expected volumes, customer locations, refund model, delivery timing, counterparties and whether you touch customer funds. Higher-risk, regulated or cross-border models may face additional underwriting.
- Formation document and EIN confirmation.
- Ownership/control chart and current IDs for relevant people.
- Business address and operating-location explanation.
- Business bank account evidence and matching ownership details.
- Clear website with product/service description and contact information.
- Terms, privacy and refund/cancellation policy where relevant.
- Plain-English transaction-flow and expected-volume summary.
- Compliance or licensing documentation if the model requires it.
Important: processor approval is discretionary. A readiness package can reduce avoidable gaps but cannot guarantee onboarding or continued processing.
Sources used
Stripe: requirements for a U.S. account · Stripe: account verification · Stripe: U.S. verification requirement updates
Processor policies can change and differ by business model and account. Always check the provider's current requirements.
Legalize coordinates payment-readiness documentation and professional handoff. It does not act as a payment processor or guarantee approval.